Nvidia (NVDA)Single company
$500,225
+900.5% price change over five years
I’m developing Alpha Investment Management with young professionals like you in mind. Before launch, I’d love to hear what you find confusing about investing—and what kind of support you would value.
Share your perspectiveA HISTORICAL ILLUSTRATION
Compare price changes alone, or explore a modeled total return that combines historical price changes with assumed dividends, rental income, and ownership costs. Compare renting a home out, living in it, or occupying part and renting out the rest. The income, savings, and costs are hypothetical—not historical records.
Q2 2021 – Q2 2026 · Stocks: June 30 closing prices · Housing: quarterly index
Adjusts the historical illustration only. This is not a forecast or investment recommendation.
Modeled total return · Before income and capital-gains taxes · No borrowing · Income held as cash, not reinvested.
Five years. Same initial cash budget for each example. Dividends and rent are constant annual amounts based on the original investment or property value, not growing annual market values. All net income is held as cash at 0% interest.
The owner-occupied model uses 100% of the property for your own housing. Its avoided rent equals the full-property annual rental value. No vacancy or management fee applies to that avoided rent. The combined model defaults to 75% owner-occupied and 25% rented out. Rental value is allocated proportionally; vacancy and management apply only to the rented share. All ownership costs apply once to the whole property.
Avoided rent is an economic benefit, not cash received or additional home equity. The displayed value assumes you actually retain those rent savings as cash at 0% interest. Stock and rental-property examples do not deduct the cost of housing their investor elsewhere: this is not a complete buy-versus-rent or equal-lifestyle wealth comparison.
The combined model assumes rentable space already exists and requires no conversion, construction, or furnishing expenditure. It does not establish whether a rental use is permitted, feasible, or desirable for a specific home. Income and avoided rent are never both counted on the same share.
The 2.6% annual ownership-cost default comprises 1.2% property tax, 0.4% insurance, and 1.0% maintenance/capital reserve, all based on the original property value. Management is 8% of rent actually collected after vacancy. Gross rent is 4% of the original property value annually, with no rent growth.
Purchase costs come out of the initial budget: property value = budget ÷ (1 + purchase-cost rate). Selling costs apply to the appreciated property value. There is no mortgage or interest. The stock dividend defaults—0.1% Nvidia and 1.5% S&P 500—are illustrative cash-yield assumptions, not measured historical yields or dividend histories.
No stock trading fees, fund expenses, or advisory fees are modeled. Income and capital-gains taxes, depreciation benefits, HOA fees, changes in tax assessments, unexpected expenses beyond the reserve, and financing are excluded. Property taxes are included in ownership costs. An actual home cannot be purchased for the small amounts shown; the property model is scaled for comparison and is not a down-payment or rent-versus-buy analysis.
$500,225
+900.5% price change over five years
$87,253
+74.5% price change over five years
$58,655
+17.3% price change over five years
—
—
Net sale proceeds + retained rent savings.
—
—
Net sale proceeds + net rent + retained rent savings.
In modeled total-return mode, housing represents an unleveraged rental property whose price follows the California index, plus assumed net rent and selling proceeds. The same starting cash budget includes purchase costs. These are illustrative assumptions—not the measured total return of an average California home. No rent is assumed for an owner-occupied home.
Ignoring dividends and costs, by , the original stock positions would have fallen to:
One selected date, not a full price history or a measure of maximum drawdown. Both stock examples had losses during this period. No corresponding housing drawdown is shown.
Nvidia was selected with hindsight because of its strong historical return. You couldn’t know this outcome in advance, and other stocks had very different results. This example illustrates what happened—not what you should expect.
For stocks, illustrative value = starting amount × observation price ÷ starting price. Nvidia uses rounded, split-adjusted closing prices of $20.00 (June 30, 2021), $11.23 (Oct. 14, 2022), and $200.09 (June 30, 2026). The S&P 500 uses closing index levels of 4,297.50, 3,583.07, and 7,499.36 on those dates. Modeled dividends are added as unreinvested cash: initial budget × assumed annual dividend yield × 5.
Price-only housing value = starting amount × 1.1731. For modeled total return: property purchase value = initial budget ÷ (1 + buying costs). Collected annual rent = purchase value × rent yield × (1 − vacancy). Annual net rent = collected rent × (1 − management rate) − purchase value × operating-cost rate. Ending wealth = purchase value × 1.1731 × (1 − selling-cost rate) + 5 × annual net rent. Owner-occupied annual net benefit = purchase value × full-property rental yield − annual operating costs. Combined annual net benefit = purchase value × rental yield × occupied share + collected rent on the remaining share × (1 − management fee) − whole-property operating costs. Avoided rent receives neither a vacancy haircut nor a management fee. Each scenario uses the same net sale proceeds. For ownership scenarios, displayed value includes net sale proceeds plus five years of net housing benefits, assuming avoided rent is retained as cash. Cumulative modeled return = displayed value ÷ initial budget − 1. Income and savings are not reinvested. The 17.31% five-year increase is FHFA’s seasonally adjusted, purchase-only California House Price Index change from Q2 2021 to Q2 2026, the latest quarterly state release available when this snapshot was prepared. The index measures repeat-sales price changes for single-family properties financed with conforming, conventional mortgages purchased or securitized by Fannie Mae or Freddie Mac. It does not represent every California home or a median/average purchase price.
Stocks use daily closes on June 30; housing uses quarterly index observations. This aligns the five-year calendar window but not the exact observation dates or methodologies. Dollar values standardize price changes to a common starting amount. They are not actual account results or a directly purchasable housing investment. Housing is shown without leverage; a mortgage would change equity returns and risk.
The historical-price view assumes continuous ownership, fractional stock shares where needed, and no later deposits or withdrawals. Price-only mode excludes dividends, rent, borrowing, and all ownership and investment costs. Modeled total-return mode uses the explicit cash-flow and cost assumptions above, with income retained as cash. Values and source prices are rounded. Price-only mode excludes income and costs. Modeled total-return mode adds hypothetical income and costs under the assumptions shown above; it is not an actual historical total-return series. The S&P 500 is an unmanaged index that cannot be purchased directly; a tracking product would have costs and tracking differences.
Historical prices with hypothetical cash-flow assumptions. Not AIM performance, actual account results, a past AIM recommendation, or personalized advice. Past performance does not predict future returns. Investing involves risk, including loss of principal.
01 / THE IDEA
You’re building a life you’re excited about. What role do you want your money to play?
I’m developing AIM with professionals in their 20s and 30s in mind, and I’d like your input on what would make financial guidance useful to you.
02 / YOUR PERSPECTIVE
I’d love to hear what you would value from a future advisory service: where you’d like support, how you’d prefer to work together, and what would help you feel confident taking the next step.
03 / MEET ADAN
A little bit about me.
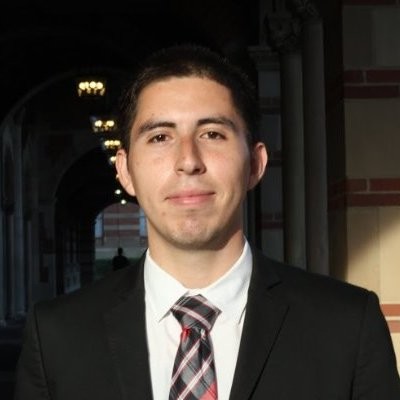
UCLA graduate Harvard MBA
Hi, I’m Adan. I’ve worked in accounting at EY, mergers and acquisitions at BDO, and strategy consulting at Boston Consulting Group.
I’ve been investing in the stock market for more than 20 years. I graduated with Latin honors in Business Economics from UCLA and earned my MBA at Harvard Business School. My aim is to make financial conversations approachable and connect your money decisions to the life you want to build.
For now, I’d welcome your perspective as I develop the business. Your experiences and feedback can help shape what comes next.
04 / LET’S CONNECT
Text me or email me to share your perspective on the planned business or request a launch update. If you’d like to talk, I’d welcome a general feedback conversation—there’s no obligation to become a client.
I’m based in Downtown Los Angeles (DTLA) and can meet in surrounding areas. We’ll find a time and place that work for you.